The Global Markets Monitor is a daily IMF report covering major global financial and economic developments.
The report is issued around 9 AM US Eastern Time, Monday to Friday.
Click here to subscribe.

- Treasury basis trade notional has fallen, but duration-adjusted exposure remains elevated
- US office property market under pressure from high delinquencies and refinancing needs
- Korean stocks extend four-day winning streak but pare gains ahead of Trump–Xi summit
- Hungary’s central bank lowers its inflation target to 2.5% from 2028, holding rates steady
- Nigeria cuts its policy rate by 350 bps, but JPMorgan puts the effective easing at 200 bps
- People’s Bank of China delivers first weaker fixing in 11 sessions ahead of Trump-Xi summit
Oil Eases as Rates Firm Again
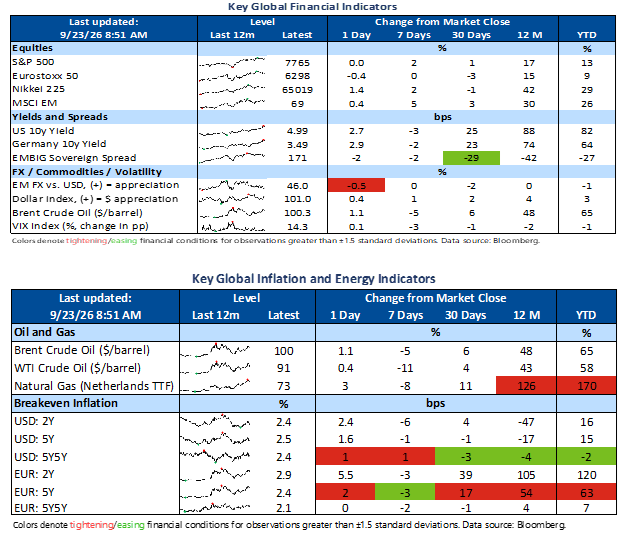
Lower oil prices have brought little relief to rate expectations, while technology shares advanced and the dollar remained firm. Brent fell below $100 yesterday on renewed hopes of a Hormuz reopening and restored Saudi pipeline capacity, before starting to drift higher again this morning. Treasury yields remained range bound as hawkish Fed commentary sustained expectations of further tightening. The Nasdaq reached its first record since June, although broader US indices slipped. In Europe, stronger services activity reversed an early bond rally and lifted ECB tightening expectations, with markets pricing firmly anchoring another hike by the end of the year. In the United Kingdom, activity softened, but rising business costs keep further BoE hikes in analysts’ forecasts. The euro and sterling weakened, while Asian equities advanced despite softer regional currencies. Attention now turns to tomorrow’s Trump–Xi summit and today’s 5-year US Treasury auction, which will test demand after a sharp rise in yields, with monetary policy uncertainty still weighing on appetite for the maturity.